The 5 Ws Sophisticated Investors Ask Before Wiring a Single Dollar.
Blue Bay Fund I
A target return means little without knowing who is underwriting it, what position your capital holds, and what happens if the deal goes sideways.
Edwin D. Epperson III
Managing Principal, Blue Bay Fund I
Five questions that separate a disciplined sponsor from a yield pitch, and how Blue Bay Fund I answers each one.
Yield is the easiest number in a private real estate deal to market and the hardest one to verify. A target return means little without knowing who is underwriting it, what position your capital actually holds, and what happens if the deal goes sideways.
The collapse of a Tampa-based REIT earlier this year, covered in our earlier article on private versus public REIT structures, is a case study in what happens when investors skip these questions entirely. Self-reported valuations went unchecked. Redemption terms were never clearly defined. Investors found out too late that nobody outside the sponsor had verified either one.
This article lays out the five questions that would have surfaced those problems before capital moved, and how Blue Bay Fund I's structure holds up when you ask the same questions.
In this context, a private real estate investment firm is a sponsor that raises capital from investors and deploys it into real estate, either as debt secured by property or as equity ownership. That differs from a publicly traded REIT, which trades on an exchange under SEC disclosure rules, and from buying a property directly, where the investor is also the operator. Evaluating a private firm means evaluating the sponsor's judgment and structure, not just the asset itself.
01 — The Problem
Why Yield-First Due Diligence Fails
Most investors evaluate a deal backward.
They start with the target return, then work toward justifying it. Sophisticated allocators reverse that order, starting with the structure and only then deciding whether the yield compensates for the risk being taken.
Private credit has grown into a real asset class. Assets under management in the space are on pace to exceed two trillion dollars in 2026, according to Moody's, and recent Federal Reserve analysis has noted that private credit has become comparable in size to the markets for bank loans and corporate bonds. That scale has attracted sponsors of highly varying discipline into the same asset class.
02 — The Framework
How to Evaluate a Real Estate Investment Firm: The 5 Ws
A useful framework does not need to be complicated. Five questions, asked in order, surface most of what matters before capital moves.
Who
Who is actually underwriting this deal, and what is their track record. Blue Bay Fund I is managed by Edwin D. Epperson III, a former U.S. Army Green Beret and Combat Diver who has personally originated more than 150 real estate deals. Before investor capital touches a single loan, Edwin funds it personally first.
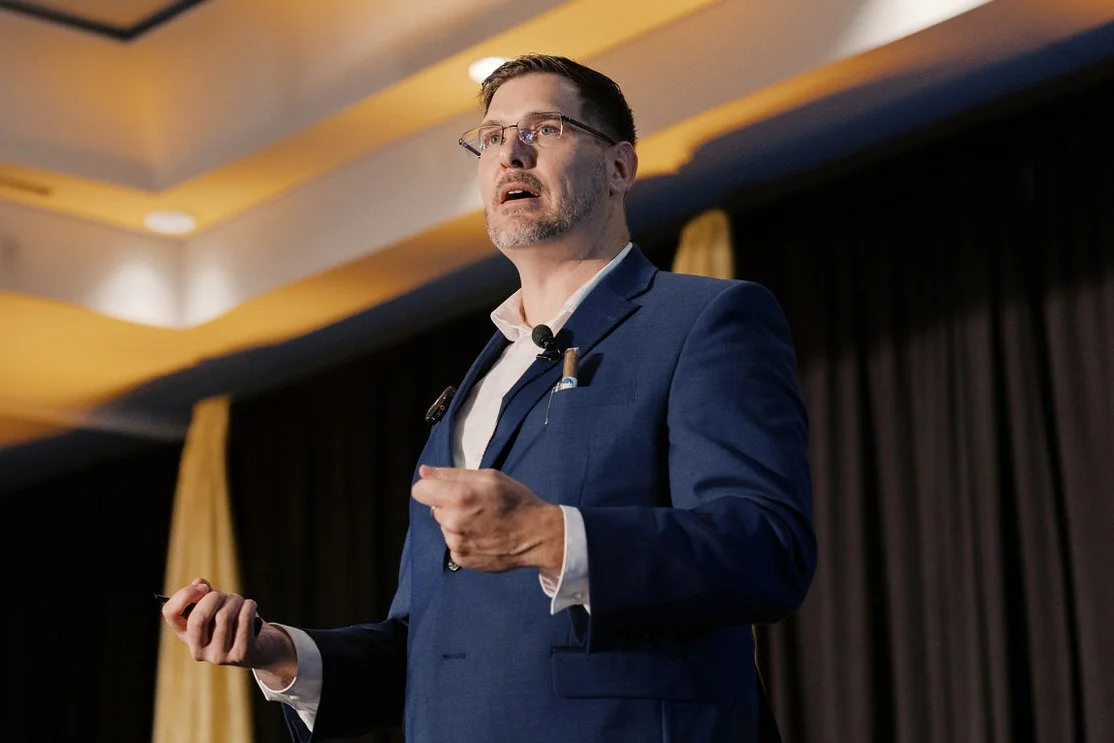
Edwin D. Epperson III
Managing Principal, Blue Bay Fund I
A manager who takes the first-loss position on every deal is underwriting the way they would with their own money, because they are. That single structural detail answers a question most sponsors avoid entirely: what happens to the manager's own capital if this loan underperforms.
What
What exactly does your capital hold, debt or equity, and where does it sit in the capital stack? Every loan Blue Bay Fund I originates holds a first-lien position on real property. First lien means your capital is repaid before subordinate debt or equity holders if a borrower defaults.
Equity investors are compensated for taking more risk, and that risk shows up in a downturn, when equity absorbs losses before any senior debt position does. Confirming which side of that line your capital sits on determines the order in which losses reach you.
When
When can you access your capital, and what triggers a distribution? Blue Bay Fund I pays monthly, not quarterly or annually. Redemption terms are defined in the fund documents upfront, not negotiated case by case after a request is filed.
Vague or unwritten liquidity terms are one of the most common gaps sponsors leave unaddressed until an investor actually needs their capital back. By then, the terms that matter most are the ones nobody wrote down.
Where
Where is the collateral located, and how concentrated is the exposure? Geographic and property-type concentration determines how correlated your losses would be if one market or sector turns. A diversified loan book behaves differently than a single large exposure, and a sponsor concentrated in one metro area is making an implicit bet on that market whether they describe it that way or not.
Why
Why does the loan-to-value ratio matter more than the yield itself? Every loan in Blue Bay Fund I is underwritten at a loan-to-value ratio under 70 percent. That threshold is the actual buffer protecting principal, not the interest rate.
Morningstar's research on sequence-of-returns risk illustrates a related principle in public markets, where the timing and order of losses matters as much as their size. In private credit, the equivalent concept is the cushion between a property's value and what it owes. A high yield sitting on top of a thin equity cushion is a worse risk-adjusted position than a moderate yield backed by real collateral coverage.
03 — Red Flags
What Weak Structures Often Hide
The five Ws double as a diagnostic for spotting funds to avoid, not just ones worth considering. A sponsor who cannot name their own co-investment percentage, who describes redemption terms as flexible rather than defined, or who cannot produce a geographic breakdown of their loan book is showing the same pattern that surfaced in the Tampa REIT case: internally set numbers with no external check, and liquidity promises that hold only until an investor tries to use them.
04 — The Math
What the Numbers Actually Show
A $500,000 allocation at Blue Bay Fund I's target yield of 10 percent produces roughly $50,000 a year, paid monthly rather than as a single annual distribution.
The comparison below shows how that structure stacks up against two common fixed income alternatives.
| CDs | Bonds | Blue Bay Fund I | |
|---|---|---|---|
| Typical yield | 4% to 5% | 4% to 4.5% (10‑year Treasury) | 8% to 12% target |
| Collateral | FDIC insured | Government or corporate credit | First lien, under 70% LTV |
| Payments | At maturity | Semiannual | Monthly |
Every figure above is a target, not a guarantee. Loan-to-value ratios and first lien position reduce the severity of a loss. They do not eliminate the possibility.
In a broader market downturn, property values can decline enough to erode even a conservative equity cushion. A borrower default still means a workout process, not an automatic recovery. First lien position gives Blue Bay Fund I the right to initiate foreclosure, but foreclosure takes time, carries its own costs, and depends on the collateral retaining enough value to make the lender whole. These are real risks of private real estate lending, regardless of which sponsor originates the loan.
The comparison matters less as a yield contest and more as a collateral contest. CDs are insured by the FDIC up to statutory limits. Bonds carry the credit of the issuer, government or corporate. Blue Bay Fund I's protection comes from the underlying real property, underwritten conservatively enough that collateral value would need to fall substantially before principal is genuinely at risk.
Closing Thoughts
The Bottom Line
The five questions above are not academic. They separate a manager who can answer confidently from one who redirects the conversation back to the yield.
Blue Bay Fund I's structure was built to answer all five without hesitation. Edwin funds every loan personally before deploying investor capital. Every loan holds a first-lien position under a 70 percent loan-to-value ceiling. Every distribution is paid monthly, on terms defined before you invest, not after.
Due diligence is not a formality that stands between an allocator and a good yield. It determines whether the yield is actually worth what it appears to promise.
Frequently Asked Questions
How do you evaluate a real estate investment firm before investing?
Ask who is underwriting the deal and their track record, what position your capital holds in the capital stack, when you can access your capital, where the collateral is located, and why the loan-to-value ratio supports the target yield.
How do you evaluate the profitability of a real estate investment?
Profitability depends on the yield relative to the risk taken to earn it. A high target yield with weak collateral protection is a worse risk-adjusted outcome than a moderate yield backed by a conservative loan-to-value ratio.
What loan-to-value ratio should a private credit fund target?
Blue Bay Fund I underwrites every loan under a 70 percent loan-to-value ratio, which provides a meaningful equity cushion before principal is at risk if a borrower defaults.
What does manager co-investment mean, and why does it matter?
Manager co-investment means the fund manager puts personal capital into a deal before deploying investor capital. Edwin D. Epperson III funds every Blue Bay Fund I loan personally first.
I have had 7 default over the last 12 years and out of 150+ investments made. This equates to an annualized default rate of our portfolio at 0.45%. As a note, the industry standard as far as an acceptable annualized rate for default is between 5.00 - 7.00% of a portfolio.
How are fees structured, and is investor capital commingled across deals?
The management fee is a spread of 0.50% to 2.50%, on the loan rate, depending on various factors of the loan that is originated. The management fee is tied to specific loan files and is not applied to the portfolio as a whole. This raises an even more important aspect of Blue Bay Fund: that our investors have the unique capability to allocate their invested dollars to specific loans. This means the underperforming loan only affects the specific investors in that investment not the portfolio as a whole.
Who can invest in Blue Bay Fund I?
Blue Bay Fund I is available to accredited investors, as defined by SEC income and net worth thresholds.
An Open Invitation
Ask Us the Five Questions
Every framework is only as good as the sponsor willing to stand behind it under direct questioning. Ask Blue Bay Fund I these five questions, and expect a specific answer to every one.
Schedule a ConsultEdwin D. Epperson III
Managing Principal, Blue Bay Fund I
With Honor,

Edwin D. Epperson III,
Manager & CEO
Soli Deo Gloria